≈ $37,500 down
Ongoing housing costs
PMI is included below since the down payment is under 20%.
Estimated total
$1,460/mo
$1,371 payment + $89 PMI
Want the occasional useful email?
New calculators, updated cost data, and the occasional money-saving guide. No account needed, and you can leave any time.
By Alex Diaz · How we calculate this
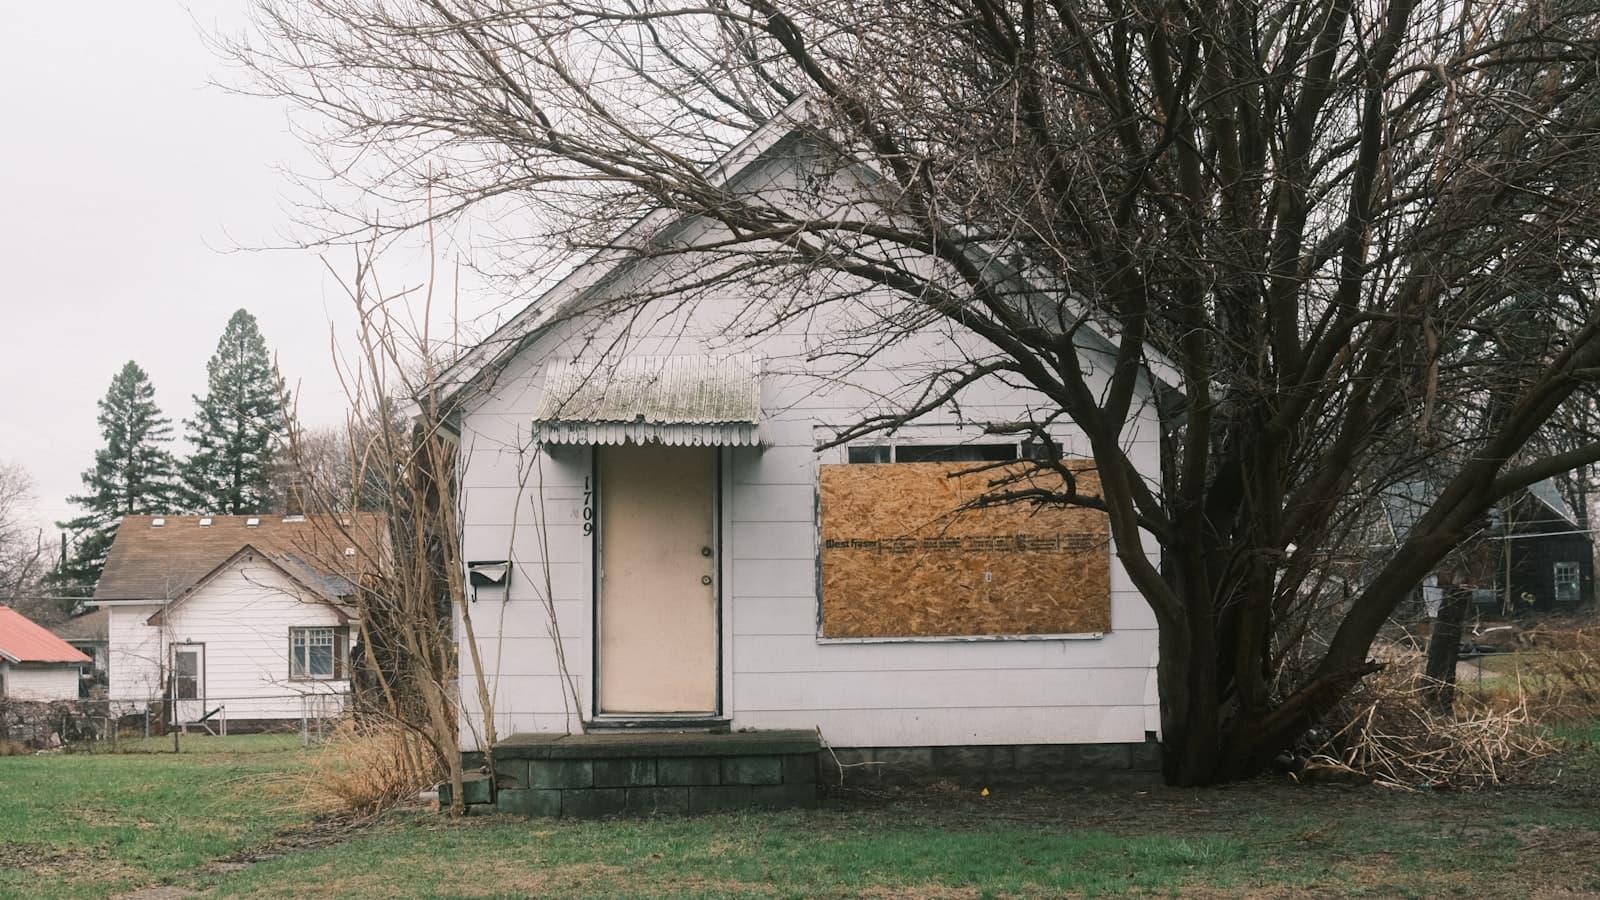
Foreclosed homes are typically sold as-is with no seller disclosures. Buying at auction usually means paying cash with little or no chance to inspect beforehand, while a bank-owned (REO) listing can often still be financed and inspected like a normal sale - two very different transactions that happen to share a label. This calculator turns the home's price, down payment, interest rate, and loan term into a monthly payment, then weighs that against your income to gauge how risky the purchase would be.
These key factors affect foreclosure affordability
Income and expenses
Yes, it's a foreclosure, but the mortgage itself works exactly like any other one. It's still a monthly payment competing against your income and whatever debt you're already carrying, and we weigh it the same way regardless of how big a discount you got on the price.
Credit score
Don't expect a discount on the mortgage rate just because you got one on the price - standard underwriting still applies, and a higher credit score still buys you a better rate. One wrinkle specific to foreclosures: a property in rough shape can be genuinely hard to finance conventionally, since some lenders won't write a loan against a home that needs major repairs before it's livable. Worth asking upfront whether the specific listing even qualifies for standard financing before you get attached to it.
Property condition and repairs
Vacant homes deteriorate fast - pipes freeze and burst, mold grows unchecked, pests move in. Since foreclosures sell as-is, whatever you find after closing is yours to fix. Budget for repairs on top of the purchase price. A discount on paper doesn't mean much if it all goes toward a new roof.
Auction vs. bank-owned purchase
These aren't the same transaction. Auction purchases typically require cash, fast, with little or no chance to walk through the property first - you're bidding largely on faith. A bank-owned (REO) listing is a different animal: it moves through a normal sale process, which usually means you can get financing and an inspection just like buying from any other seller.
Down payment and loan term
Nothing unusual here. More down means less borrowed, and a longer term trades a lower payment for more interest paid over time, exactly like it would on any other mortgage.
How to use your results
Try adjusting the inputs to see what actually moves your risk score:
- Foreclosure price - include an estimate for repairs if the property needs work, not just the sale price.
- Down payment and loan term - see how each moves your monthly payment and risk score.
- Existing debt - add what you're already carrying for a more realistic picture.
Ways to increase how much foreclosure you can afford
- Get an inspection whenever possible before committing, especially outside of an auction setting.
- Pay down existing debt to improve your debt-to-income ratio before applying for a mortgage.
- Save for a larger down payment to borrow less and leave room for repairs.
- Budget for repairs upfront rather than treating the discounted price as the full picture.
More housing calculators
Peer comparison data
Bureau of Labor Statistics (median income by age), Experian (credit score by age)
Used by the “how you compare” figures in the sidebar, not by the costs on this page.
Every figure on this site, with its source and the date it was last verified
How you compare
Income
Credit score
Nothing added yet - add something to see your risk.