≈ $35,000 down
Ongoing housing costs
PMI is included below since the down payment is under 20%.
Estimated total
$2,164/mo
$2,033 payment + $131 PMI
Want the occasional useful email?
New calculators, updated cost data, and the occasional money-saving guide. No account needed, and you can leave any time.
By Alex Diaz · How we calculate this
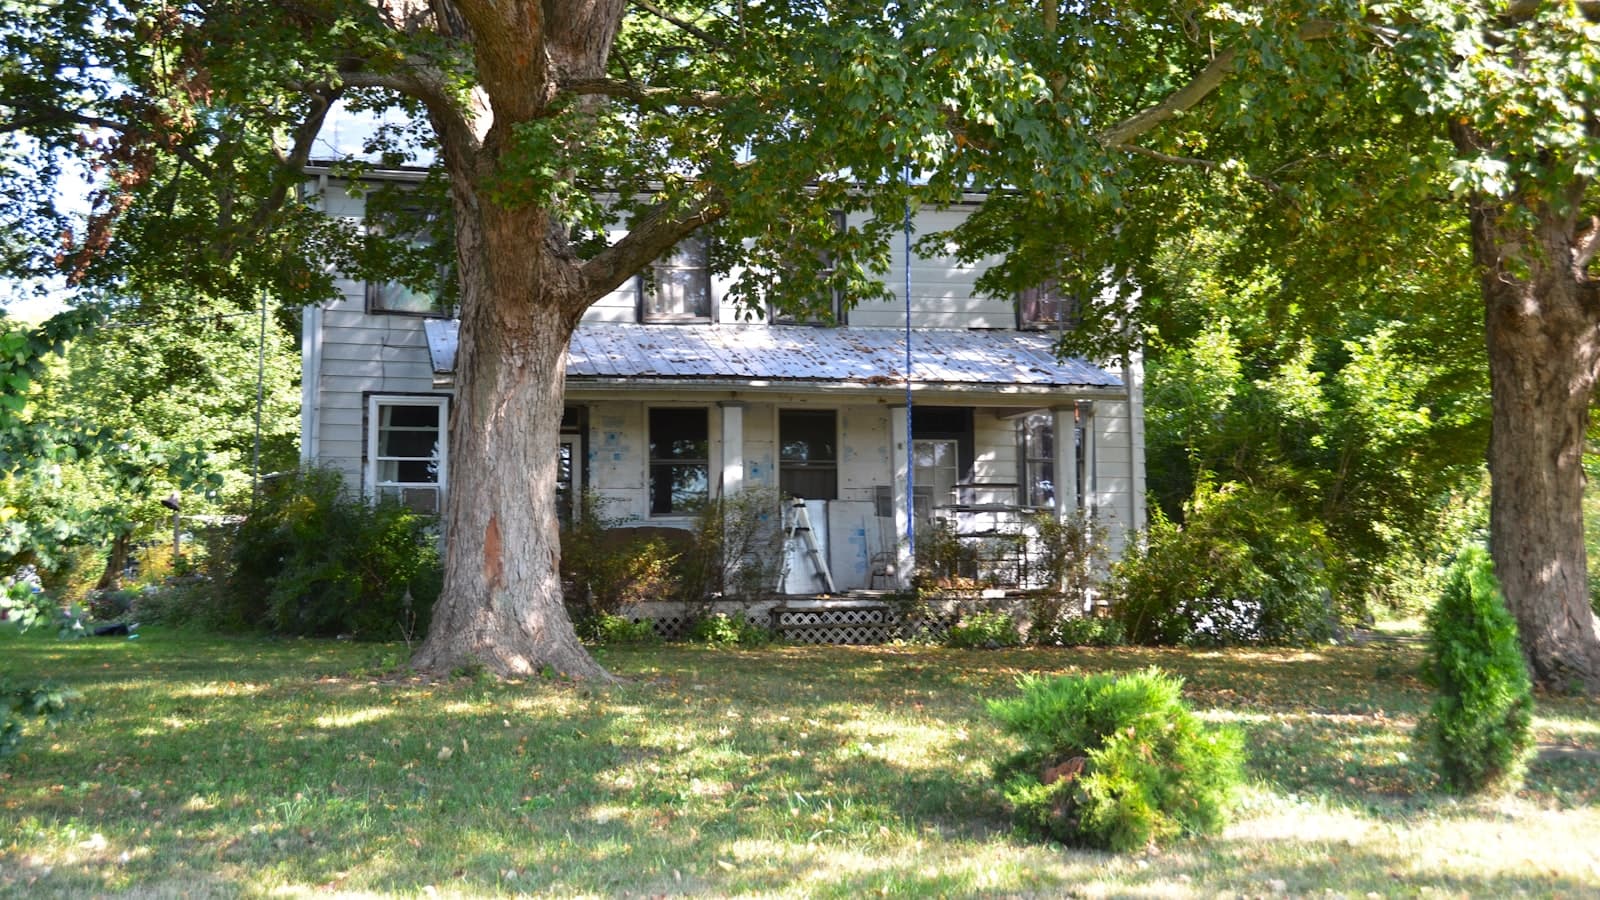
There's a specific loan built for exactly this situation: an FHA 203(k) rolls the purchase price and the renovation budget into one mortgage, so you're not scrambling to line up separate financing for repairs on top of the home loan. This calculator adds the price and repair costs together, works out the payment at the down payment, rate, and term you enter, and weighs that against your income to gauge how risky the purchase would be.
These key factors affect fixer-upper affordability
Income and expenses
A fixer-upper asks more of your budget than a move-in-ready home does, because you're not just paying for the house - you're paying for the house and the work it needs, at the same time. We weigh that combined number against your income and whatever debt you've already logged, since that's the real monthly obligation.
Credit score
A 203(k) or other renovation loan comes with its own underwriting on top of a standard mortgage's, and credit score cuts both ways here: a lower score doesn't just mean a worse rate, it can also shrink how much you're allowed to borrow for the repair portion itself.
Repair cost estimates
Nearly every fixer-upper buyer underestimates repair costs the first time through - it's less a rookie mistake than a near-universal one. A professional inspection and a real contractor estimate before closing, not a guess based on the walkthrough, is what actually gets you a number you can trust.
Contingency budget
Open up an old wall and you find out what's actually been going on behind it - outdated wiring, old pipes, framing that wasn't done right the first time. That's exactly why a contingency on top of the quoted repair cost is standard advice, not caution for its own sake.
Down payment and loan term
These two work the way they always do: more down means less to borrow, and a longer term trades a lower monthly payment for more interest paid over the life of the loan.
How to use your results
Try adjusting the inputs to see what actually moves your risk score:
- Total price plus repairs - use a contractor estimate plus a contingency, not just the purchase price.
- Down payment and loan term - see how each moves your monthly payment and risk score.
- Existing debt - add what you're already carrying for a more realistic picture.
Ways to increase how much fixer-upper you can afford
- Get a professional inspection before making an offer to avoid underestimating repair costs.
- Look into a renovation loan that rolls repair costs into a single mortgage at a set rate.
- Budget a contingency beyond the quoted repair estimate for unexpected issues.
- Pay down existing debt before applying so more of your qualifying income goes toward this purchase.
More housing calculators
Peer comparison data
Bureau of Labor Statistics (median income by age), Experian (credit score by age)
Used by the “how you compare” figures in the sidebar, not by the costs on this page.
Every figure on this site, with its source and the date it was last verified
How you compare
Income
Credit score
Nothing added yet - add something to see your risk.