≈ $140,000 down
Ongoing housing costs
Estimated total
$3,851/mo
Want the occasional useful email?
New calculators, updated cost data, and the occasional money-saving guide. No account needed, and you can leave any time.
By Alex Diaz · How we calculate this
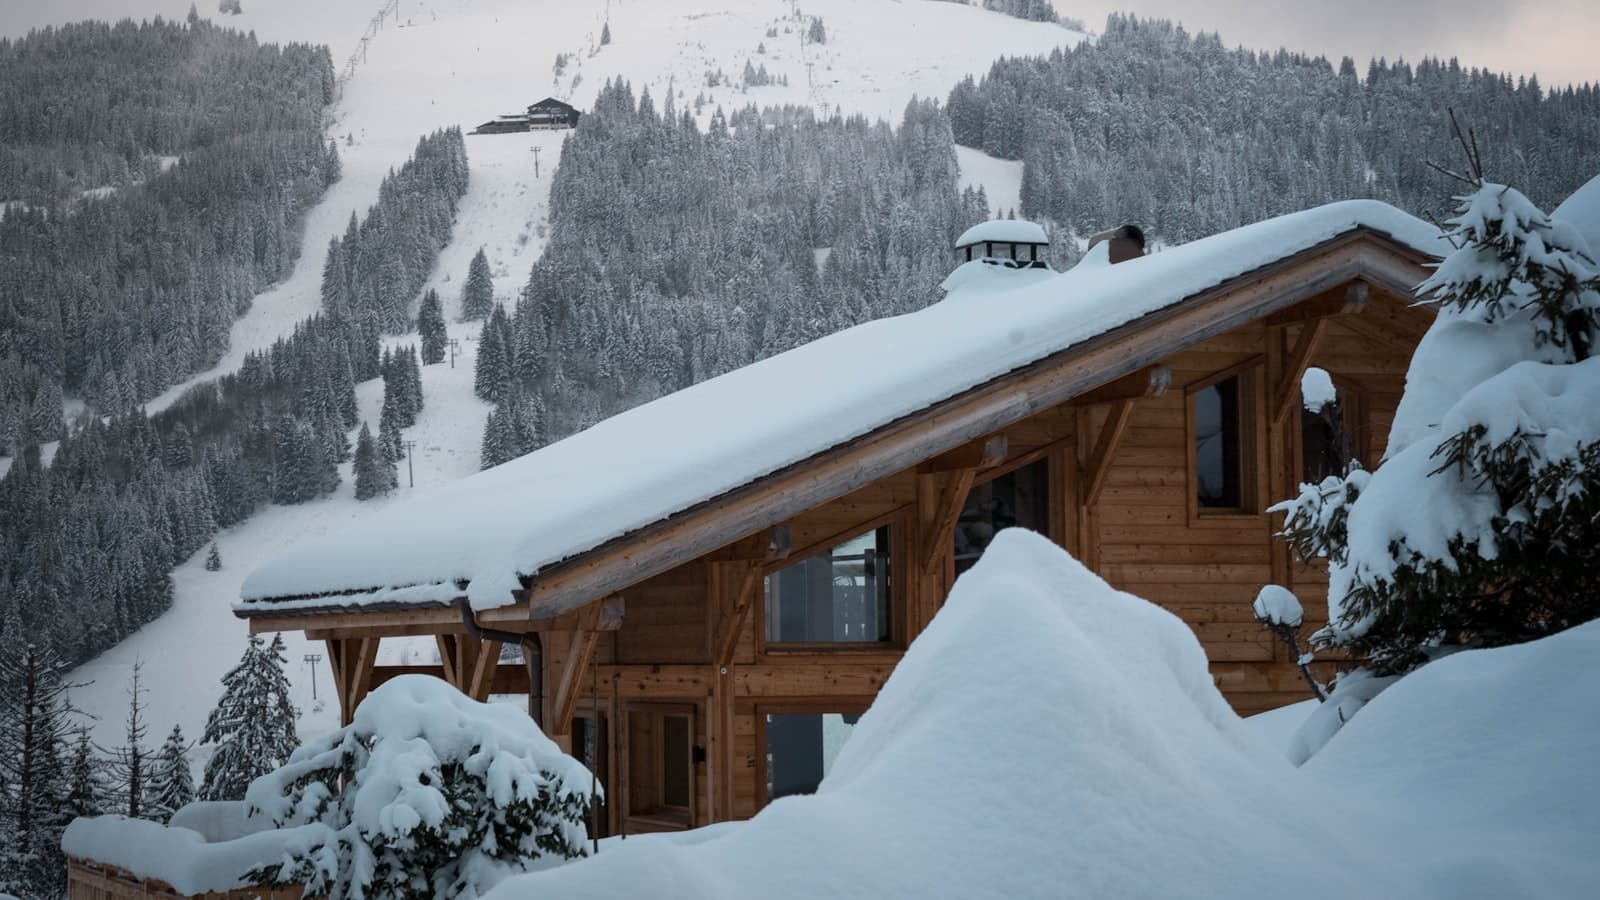
Lenders generally treat a ski chalet as a second home, requiring a larger down payment and charging a higher rate than they would for a primary residence mortgage. Your estimate combines the chalet's price, down payment, rate, and term into a monthly payment, then weighs that against your income, existing debt, and credit score.
These key factors affect ski chalet affordability
Income and expenses
A ski chalet payment has to share your budget with everything else you owe, and that gets more complicated if you're carrying a primary residence mortgage at the same time. We weigh the full payment against your income and any other debt you've already logged, not against the chalet's price alone.
Credit score
Mountain and resort-area homes can be harder to appraise than a typical suburban property simply because there are fewer comparable sales nearby, and lenders lean more heavily on your credit profile when the collateral itself is harder to pin down. Layer that on top of the stricter underwriting second homes already get compared to a primary residence, and a weaker credit score has an outsized effect on your rate here.
Seasonal use and snow load
Mountain properties are built to a snow load rating set by the local building code, and both that rating and the cost of meeting it tend to climb with elevation and annual snowfall, so it's worth confirming the roof and structure are actually rated for where the property sits. Access can be seasonal too, a private road that's an easy drive in July can mean plowing costs or limited access during a heavy snow month. A chalet that sits empty for stretches of the off-season also needs winterizing, and often a monitored heat source, since many second-home policies exclude frozen-pipe damage if a home was left unheated and unchecked for too long.
Down payment and loan term
Plan on putting down more than you would for a primary residence. Conventional second-home loans commonly call for at least 10 percent down, and a lender may ask for more if the chalet sits somewhere remote with a thin resale market, that's cash you need on hand beyond whatever you've already put into your primary home.
Rental potential
Chalets near a resort town can often be rented out during peak ski season, and that income can meaningfully offset the payment. Price it conservatively though, a slow snow year or a soft rental market can leave weeks unbooked, so don't count on it filling every week of winter.
How to use your results
Try adjusting the inputs to see what actually moves your risk score:
- Down payment - second-home loans often require more down than a primary mortgage.
- Existing debt - include your primary mortgage if you're carrying one alongside this purchase.
- Rental income - model a conservative peak-season estimate if you plan to rent it out.
Ways to increase how much ski chalet you can afford
- Pay down existing debt, including your primary mortgage if possible, before taking on a second one.
- Save for a larger down payment, since second-home loans often require more down.
- Consider renting the property out during peak ski season to help offset the payment and upkeep.
- Get real insurance and maintenance quotes for the specific climate before committing to a price range.
More housing calculators
Peer comparison data
Bureau of Labor Statistics (median income by age), Experian (credit score by age)
Used by the “how you compare” figures in the sidebar, not by the costs on this page.
Every figure on this site, with its source and the date it was last verified
How you compare
Income
Credit score
Nothing added yet - add something to see your risk.