≈ $3,500 down
Taxes & fees
Ongoing vehicle costs
Estimated total
$567/mo
Want the occasional useful email?
New calculators, updated cost data, and the occasional money-saving guide. No account needed, and you can leave any time.
By Alex Diaz · How we calculate this
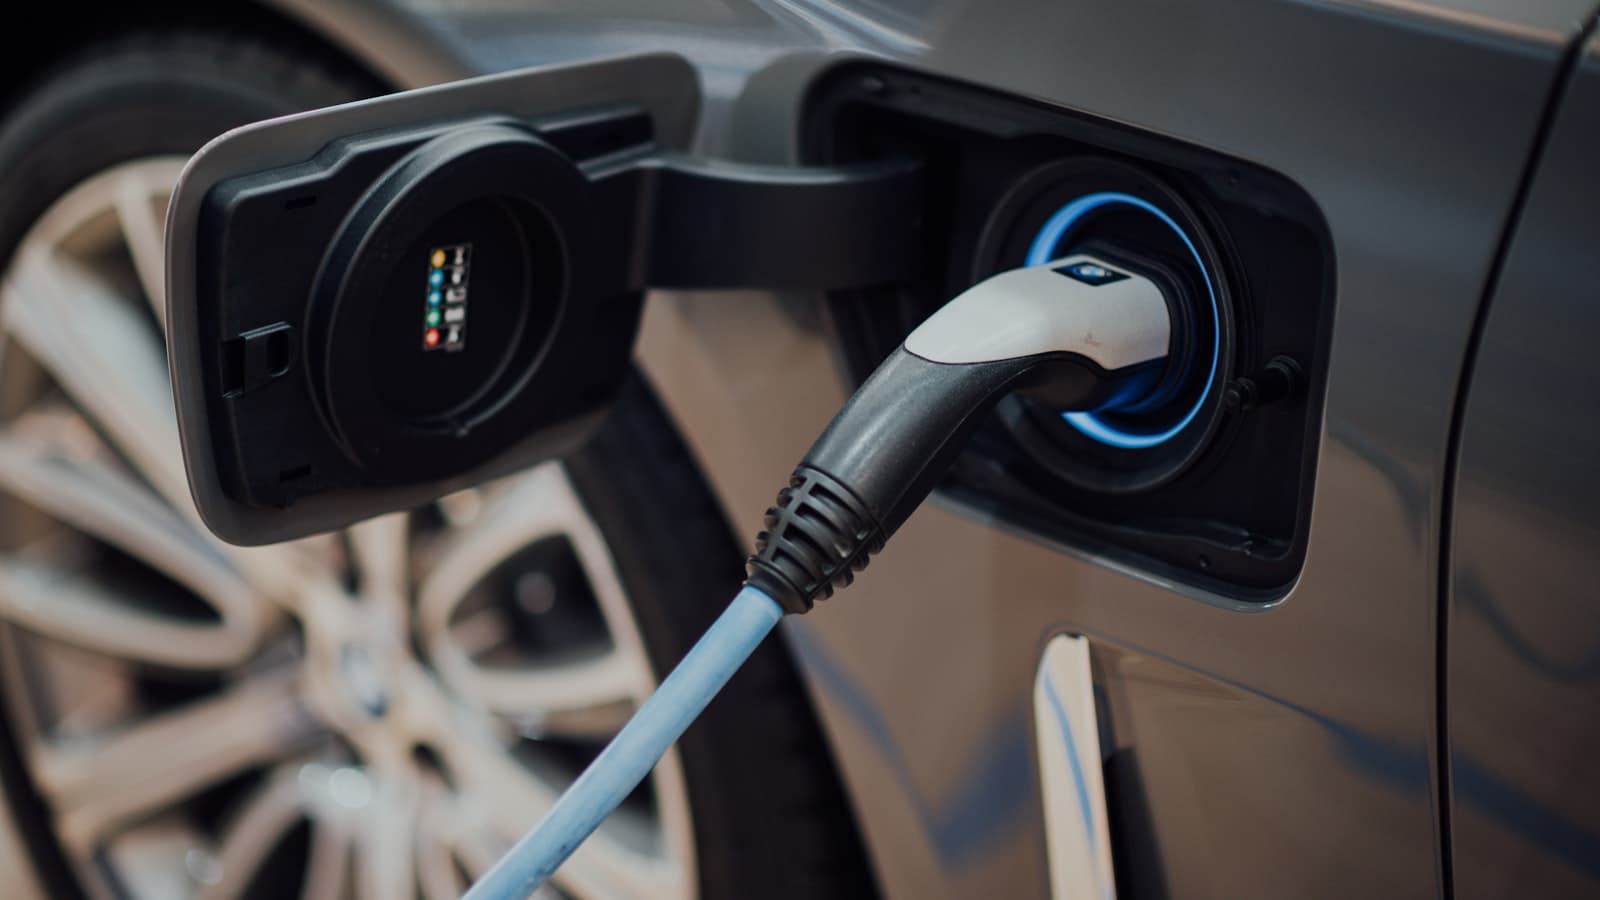
A hybrid typically costs more upfront than a comparable gas-only model, though the fuel savings add up over time. Enter the car's price, down payment, rate, and loan term and the calculator turns that into a monthly payment, then checks it against your income to see how much risk the purchase would carry.
These key factors affect hybrid car affordability
Income and expenses
Whatever the payment on a hybrid works out to, it's competing with your rent or mortgage, groceries, and any other debt already on the books, so we weigh it against your full financial picture rather than in isolation.
Credit score
Rates on auto loans move a lot with credit tier, and that gap in interest costs the same dollar amount whether the car under the hood is a hybrid or not. If your score is on the lower end, expect the rate quoted to reflect that, and shop more than one lender before signing.
Fuel savings and tax credits
A hybrid usually costs more to buy than the gas-only version of the same car, but it burns less fuel, and that gap narrows the math over years of ownership. Tax credits are a smaller factor than they used to be: the federal credit for new clean vehicles mainly applied to plug-in hybrids with a large enough battery, not standard (non-plug-in) hybrids, and it expired for vehicles acquired after September 30, 2025, so don't count on a federal credit unless the rules change again. A handful of states still offer their own rebates or tax breaks for efficient vehicles, so it's worth checking your state's program before assuming there's nothing available.
Battery life and resale value
Hybrid batteries carry a required warranty of at least 8 years or 100,000 miles, and in California and the other states that follow its emissions rules, that stretches to 10 years or 150,000 miles. In practice, hybrid battery packs have tended to outlast that warranty by a wide margin, so a failure serious enough to need a full pack replacement outside of it isn't the norm. That reliability is part of why hybrids have historically held their resale value better than an equivalent gas car.
Down payment and loan term
Putting more down reduces what you finance, and a longer term brings the monthly payment down too, at the cost of more interest paid over the life of the loan, worth remembering since the fuel savings that make a hybrid appealing take longer to show up if the loan itself is stretched out.
How to use your results
Try adjusting the inputs to see what actually moves your risk score:
- Down payment - a bigger down payment shrinks the loan and often the payment.
- Loan term - compare a shorter term's higher payment against a longer term's lower one.
- Existing debt - add what you're already carrying for a more realistic picture.
Ways to increase how much hybrid car you can afford
- Pay down existing debt before taking on a new car payment.
- Check whether your state offers a rebate or tax break for efficient vehicles, since the federal credit for new clean vehicles ended for vehicles acquired after September 30, 2025.
- Shop your loan - credit unions and banks often beat dealer financing.
- Consider a certified used hybrid instead of new to reduce the loan amount.
More vehicles calculators
Sources
Bankrate (average auto loan rate), Tax Foundation / Avalara (state vehicle sales tax rates), Policygenius (national average vehicle sales tax), CarEdge (average dealer documentation fee), GeoNames (ZIP code/city lookup)
Starting points to compare against, not real-time quotes.
Peer comparison data
Bureau of Labor Statistics (median income by age), Experian (credit score by age)
Used by the “how you compare” figures in the sidebar, not by the costs on this page.
Every figure on this site, with its source and the date it was last verified
How you compare
Income
Credit score
Nothing added yet - add something to see your risk.